CONTENT
Daqo New Energy sits near the beginning of China’s solar manufacturing chain. It converts metallurgical-grade silicon into high-purity polysilicon, which customers turn into ingots, wafers, cells, and modules. Its 305,000 metric tons of annual nameplate capacity spans Xinjiang and Inner Mongolia, yet its latest results show why installed scale alone can mislead.
Low prices, idle assets, inventory, and trade controls can outweigh cost advantages. The company matters because its performance reveals how China’s upstream solar supply chain now balances quality, power costs, capacity discipline, and access to overseas markets.
Daqo New Energy specializes exclusively in solar-grade silicon, the foundational material for photovoltaic wafers. The company’s production process transforms metallurgical-grade silicon into 99.9999% pure polysilicon through a modified Siemens process. This material directly feeds into wafer manufacturing, which ultimately determines solar cell efficiency.
Polysilicon is the chemical bridge between industrial silicon and a solar cell. Daqo uses the modified Siemens process with upgraded hydrochlorination and closed-loop recovery. Metallurgical-grade silicon becomes purified chlorosilanes, then chemical vapor deposition forms ultra-pure rods.
The crushed result is solar-grade silicon feedstock for ingot growth. The process needs continuous electricity, steam, and water, making energy reliability central to output and production costs.
The company sells to China-based wafer producers and vertically integrated solar manufacturers. Wafer manufacturing therefore sits downstream from Daqo.
Higher-purity material supports mono-wafer and N-type cell production, where contamination control affects yield and electrical performance. Daqo’s three largest customers generated 63.5% of 2025 revenue, tying performance to a small buyer group.
The NYSE-listed parent is a Cayman Islands holding company. It beneficially owned about 72.8% of Xinjiang Daqo as of March 31, 2026. The operating subsidiary has its own STAR Market listing, minority shareholders, and board. Inner Mongolia Daqo New Energy sits below Xinjiang Daqo and runs the Baotou base.
The distinction matters because the parent reports under US GAAP in dollars, while the Shanghai-listed subsidiary reports under PRC rules in renminbi.
| Entity | Role in the group | Current strategic relevance |
| Daqo New Energy Corp | NYSE-listed holding company | Gives investors exposure to the consolidated group and the parent’s share of operating results. |
| Xinjiang Daqo New Energy (Xinjiang Daqo) | Principal operating subsidiary and STAR Market company | Holds the core polysilicon business and controls the Inner Mongolia unit. |
| Inner Mongolia Daqo New Energy | Manufacturing subsidiary | Operates 200,000 metric tons of nameplate capacity in Baotou. Xinjiang accounts for the other 105,000 metric tons. |
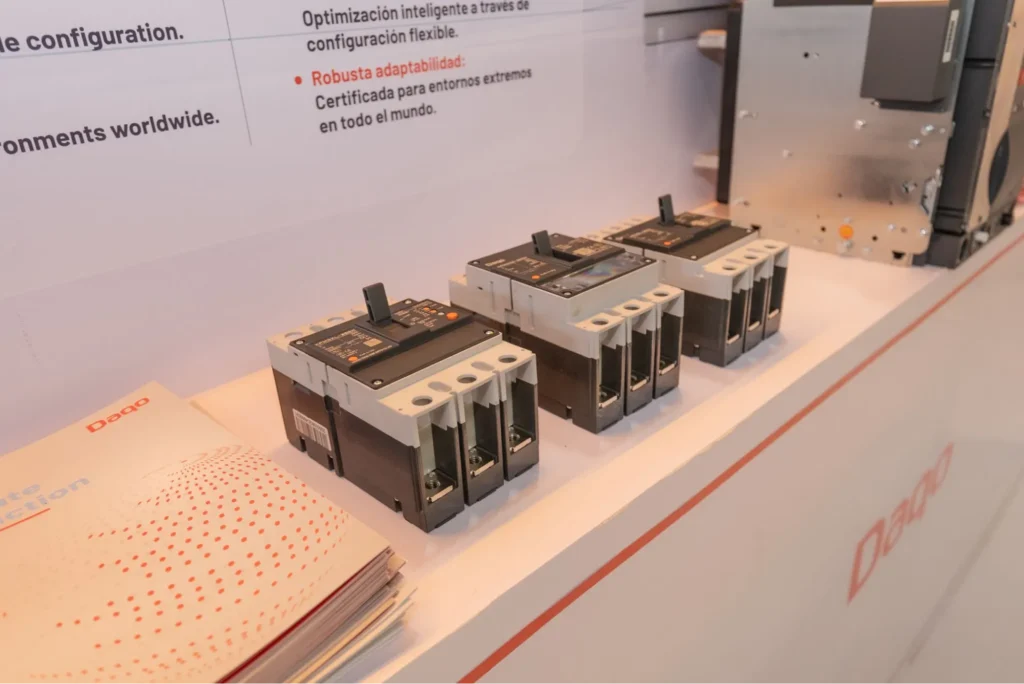
Manufacturing capacity sets a ceiling, while actual output shows market discipline. Daqo produced 123,652 metric tons in 2025, roughly 41% of its 305,000 metric tons of nameplate capacity. It sold 126,707 metric tons, recorded $665.4 million in revenue, and reported a $170.5 million net loss attributable to parent shareholders.
| Metric | Full year 2025 | First quarter 2026 |
| Production volume | 123,652 MT | 43,402 MT |
| Sales volume | 126,707 MT | 4,482 MT |
| Average selling price | $5.25/kg | $5.96/kg |
| Net loss attributable to parent shareholders | $170.5 million | $88.4 million |
The first quarter of 2026 made the cycle visible. Daqo produced 43,402 metric tons but sold 4,482 after management declined below-cost transactions. Revenue fell to $26.7 million, while inventory impairment contributed to a $139.4 million gross loss.
Total production cost reached $5.95 per kilogram and cash cost reached $4.59. The group reported $2.0 billion of cash and near-cash assets and said it had zero debt.
A low cash cost can support survival, but idle depreciation, inventory write-downs, and weak prices can erase accounting profit. The spread between cash cost, total cost, and realized price says more than capacity alone.
China’s industry overcapacity remains severe. At a July 2026 seminar, China Photovoltaic Industry Association data indicated about 3.5 million metric tons of expected nameplate capacity, first-half production near 540,000 metric tons, and average utilization of 33.8%. Inventory stood near 500,000 metric tons, while prices had dropped below cash production costs for most manufacturers.
Bernreuter Research placed the global spot average at $4.78 per kilogram on July 30, 2026, and China’s N-type material at RMB 31.5 including tax. Product grade, tax, contract terms, and timing prevent a mechanical comparison with company costs.
New national standards take effect on January 1, 2027. Existing Siemens-process facilities must meet the Grade 3 ceiling of 6.3 kilograms of standard coal equivalent per kilogram. New, expanded, or upgraded capacity must meet the Grade 2 threshold of 5.5. Much of the least efficient capacity already sits idle, so formal compliance may reduce nominal capacity faster than actual supply.
Western and northern China give Daqo access to lower-cost electricity and raw materials, but power source and energy intensity carry separate commercial consequences. The 2025 ESG report states that its Inner Mongolia operation sourced 85% of annual electricity from clean power. Daqo presented this against its group goal for clean energy to exceed 80% of total consumption by 2030.
Clean electricity share does not prove compliance with China’s new unit-energy ceiling. Buyers need both measures. One shows the carbon profile of power, while the other shows how much total energy a plant consumes per kilogram of output.
Plant-level evidence will become more valuable as manufacturers make low-carbon procurement claims and Chinese regulators test technical compliance.
Daqo’s 2025 annual filing says Xinjiang Daqo remains on the US Uyghur Forced Labor Prevention Act Entity List and the Commerce Department’s Entity List. The company states that it does not tolerate forced labor in its facilities or supply chain.
It also acknowledges that US authorities may restrict downstream products containing its polysilicon. This creates an admissibility and documentation issue for modules several stages removed from the original material.
Daqo sells primarily inside China, so US exposure travels through customers that turn its material into wafers, cells, and modules. Effective traceability must preserve the link from a polysilicon lot through each conversion stage. A supplier declaration at the module level offers limited assurance without production records and transaction documents underneath it.
Tariffs present a separate risk. The US Commerce Department opened a Section 232 investigation into polysilicon and derivatives in July 2025.
On August 4, 2026, Reuters reported that the US administration was preparing a minimum import price and new tariffs, with a decision expected later in August. The measure was still pending at publication, so companies should model it as a scenario rather than a settled rule.
Daqo shows that scale, cost, quality, and market access now work as one operating system. A useful monitoring framework should include:
Daqo also started looking beyond polysilicon. A Shanghai subsidiary signed a June 2026 agreement for a Kunshan base serving AI data-center energy systems. Phase one carries a planned investment of RMB 2.1 billion. The company said the performance impact remains undetermined.
The near-term thesis still rests on polysilicon. Price recovery must meet production discipline, inventory control, technical compliance, and credible provenance. Those tests will decide which producers carry scale through future market cycles.
Daqo’s disclosures reveal the gap between capacity, production, sales, and profitability. They may leave your team with harder questions.
ChoZan’s Expert Calls connect your team with vetted specialists across China’s technology and business sectors, including green tech. Submit three to five questions in advance. ChoZan researches your industry and competitors, presents relevant expert profiles, briefs the selected specialist on your objectives, and provides follow-up after the consultation.
Use the conversation to test an investment thesis, clarify a policy development, prepare for a supplier discussion, or understand a competitive shift before committing resources.
Book a consultation with ChoZan to match your questions with the right China expert.
Daqo New Energy does not currently manufacture finished solar panels. Its 2025 filing describes a focused upstream business that sells high-purity polysilicon to China-based manufacturers, which convert the material into ingots, wafers, cells, and modules.
Production sits in Shihezi, Xinjiang, and Baotou, Inner Mongolia. The 2025 annual report assigns 105,000 metric tons of nameplate capacity to Xinjiang and 200,000 metric tons to Inner Mongolia, totaling 305,000 metric tons.
As of March 31, 2026, the parent beneficially owned about 72.8% of Xinjiang Daqo. The subsidiary trades separately on Shanghai’s STAR Market, so minority shareholders share its economics and influence its governance.
Yes. Daqo New Energy Corporation commonly refers to the NYSE-listed parent whose formal name is Daqo New Energy Corp. Corporate documents use the shortened legal form “Corp.”, while search queries may spell out “Corporation.”
Each Daqo New Energy Corp American depositary share listed on the New York Stock Exchange under DQ represents five ordinary shares. This US-listed ADR gives access to the Cayman parent rather than direct ownership of STAR-listed Xinjiang shares.
Cash cost excludes depreciation and noncash share compensation, while total production cost includes inventoriable depreciation. The gap matters in a downturn because a plant can cover immediate cash inputs yet still lose money after fixed-asset costs.
N-type solar cells require very clean feedstock because metallic and other impurities can reduce electrical performance. This raises the commercial value of consistently high-purity polysilicon, although qualification, yield, and price still determine the supplier’s advantage.
The company says it typically does not sell polysilicon directly into the United States. Its China-based customers may export wafers, cells, or modules, so US import controls can reach Daqo indirectly through downstream origin and traceability.
Principal Daqo New Energy subsidiaries in the operating chain include Xinjiang Daqo and Inner Mongolia Daqo New Energy. The parent’s 2025 filing also lists holding, research, recycling, Hong Kong investment, and semiconductor-material entities.
A buyer should request plant-level origin records, lot mapping through wafer and cell stages, energy-consumption data, clean-electricity evidence, supplier declarations, and jurisdiction-specific legal review. A generic ESG report cannot replace shipment-level chain-of-custody documentation.